The Upper Tribunal has ruled in favour of hair replacement provider Mark Glen Ltd in a significant VAT appeal, overturning an earlier decision after criticising the lower tribunal’s reasoning as inadequate.
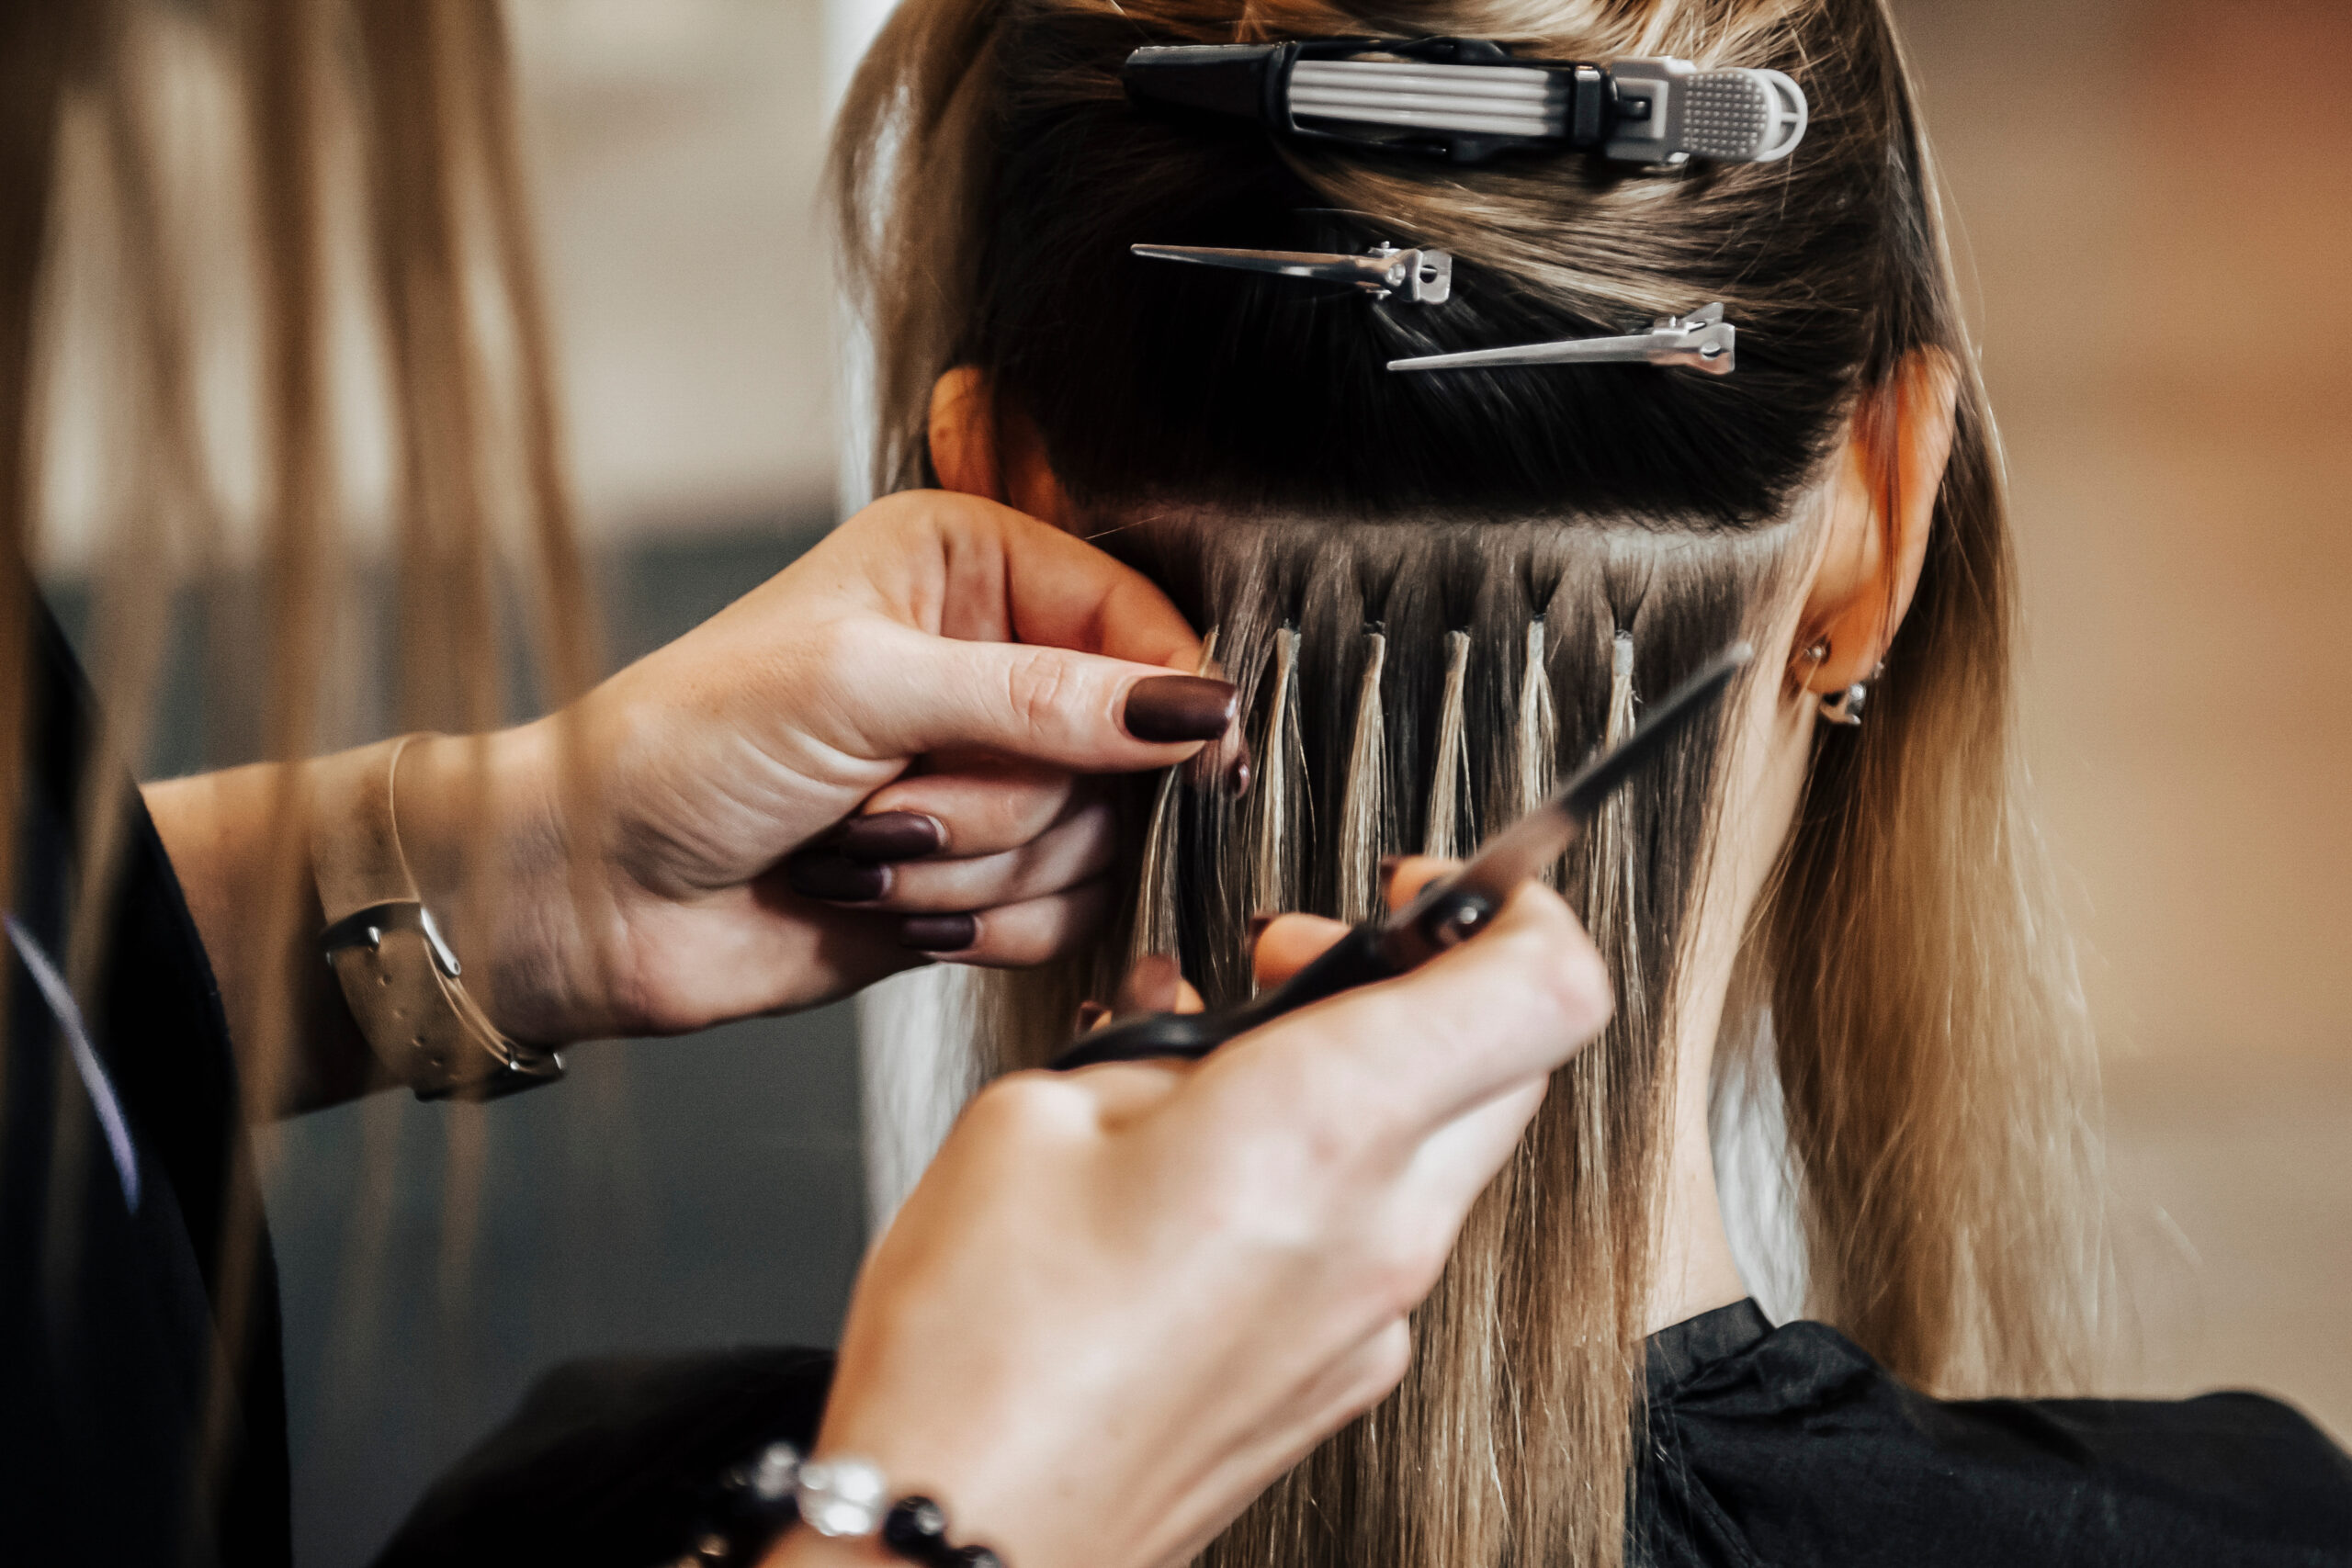
Mark Glen Ltd supplies wigs and hair extension systems to NHS patients and had argued that its services should qualify for VAT zero rating on medical grounds. The business described its activities as providing ‘hair extensions and medical treatments for follicularly challenged’ individuals.
HMRC issued a £277,000 VAT assessment, contending that the supplies did not qualify for zero rating. The First Tier Tribunal (FTT) initially sided with HMRC, leaving the company facing a six-figure VAT liability.
The legal issue
The appeal before the Upper Tribunal focused on whether the company’s hair loss replacement system, known as the ‘Kinsey system’, qualified for zero rating under Schedule 8 Group 12 (Drugs, medicines, aids for the disabled, etc) of the Value Added Tax Act 1994 (VATA 1994). Specifically, the question was whether the supplies fell within Item 3, as a supply to a disabled person of services adapting goods to suit their medical condition.
Representing Mark Glen Ltd, tax barrister and Jersey advocate Harriet Brown of Old Square Tax Chambers argued that the FTT ‘erred in law in that its reasoning was inadequate or else otherwise flawed in various respects’.
Referring to Edwards v Bairstow, Brown also challenged the FTT’s conclusion that ‘baldness in women was not a disability was one that no reasonable tribunal could have reached on the evidence’, describing that finding as ‘perverse’. The Upper Tribunal, however, did not accept this particular argument.
Adequacy of reasoning
A central theme of the appeal was whether the FTT had properly explained its decision.
HMRC maintained that the lower tribunal had provided ‘good and sufficient reasons’, noting that it had considered oral evidence from the appellant’s witness, Mr Kinsey, the inventor of the hair extension treatment, although HMRC argued that his evidence was not decisive.
In delivering the Upper Tribunal’s judgment, Judge Raghavan explained that the court ‘drew on the well-established principles in Flannery and English. In summary the duty to give reasons requires the decision-maker to expose reasoning sufficient to allow the parties and an appellate court to understand why the case was decided as it was’.
Judge Raghavan observed that the FTT had failed to grapple properly with the central dispute between the parties, namely whether the severe hair loss experienced by the women in question amounted, in itself, to a disability.
He stated: ‘It is apparent that the FTT did not confront the central point of contention between the parties with respect to whether the severe hair loss at issue on the facts amounted to disability in and of itself.
‘There were clearly two competing views on the approach to that issue regarding whether any consideration of impact on everyday activities was limited to physical limitation, as advanced by HMRC, or whether it should take account of the wider social context, as the appellant’s case entailed.’
Impact of severe hair loss
Addressing the FTT’s handling of evidence regarding the effect of severe hair loss on women, Judge Raghavan highlighted a significant omission. He noted: ‘The omission of explanation on this key point of contention was all the more conspicuous given the FTT itself acknowledged Mr Kinsey’s evidence that “hair loss affects women’s lives in so many different ways and that it impacted every area of their lives”.’
He added that he would have expected the FTT to examine ‘whether those “many different ways” spoke to day-to-day activities…but the decision does not expose what the FTT analysis in that respect was’.
The Upper Tribunal emphasised that extensive reasoning was not required. Judge Raghavan clarified that ‘for the reasoning to be adequate it did not need to be lengthy. It simply needed to explain, perhaps in no more than a paragraph or so, why the appellant’s case (that hair loss of the type involved was a disability in and of itself) was being rejected’.
The failure to provide that explanation proved decisive. Rejecting HMRC’s position, the Upper Tribunal upheld the appeal on the grounds of ‘inadequacy of reasoning and interpretation of Item 3’.
Late argument rejected
The tribunal did, however, dismiss a further argument raised late by the appellant’s legal team. They had contended that the supply was of goods rather than services. The tribunal ruled that HMRC had not been given sufficient notice to respond to this additional ground.
Judge Raghavan commented: ‘Allowing the new point would in our view cause real prejudice to HMRC. HMRC also prepared their case on the footing of a services-only supply.’
Final outcome
In concluding its decision, the tribunal stated, within the ambit of the Mark Glenn Ltd case: ‘For present purposes, however, severe hair loss in women of the type relevant to this case is, in our view, disabling… We stress that our decision is confined to the facts of this case and to women who experienced baldness in the form of severe and patchy hair loss.’
The tribunal determined that ‘each of the supplies in question were therefore supplies which fell within the terms of Item 3 of Group 12 and were therefore zero-rated’.
The original FTT decision was set aside and remade by the Upper Tribunal, and the appeal was therefore allowed.
An HMRC spokesperson said: ‘We note the decision of the tribunal and will carefully consider the judgment.’
