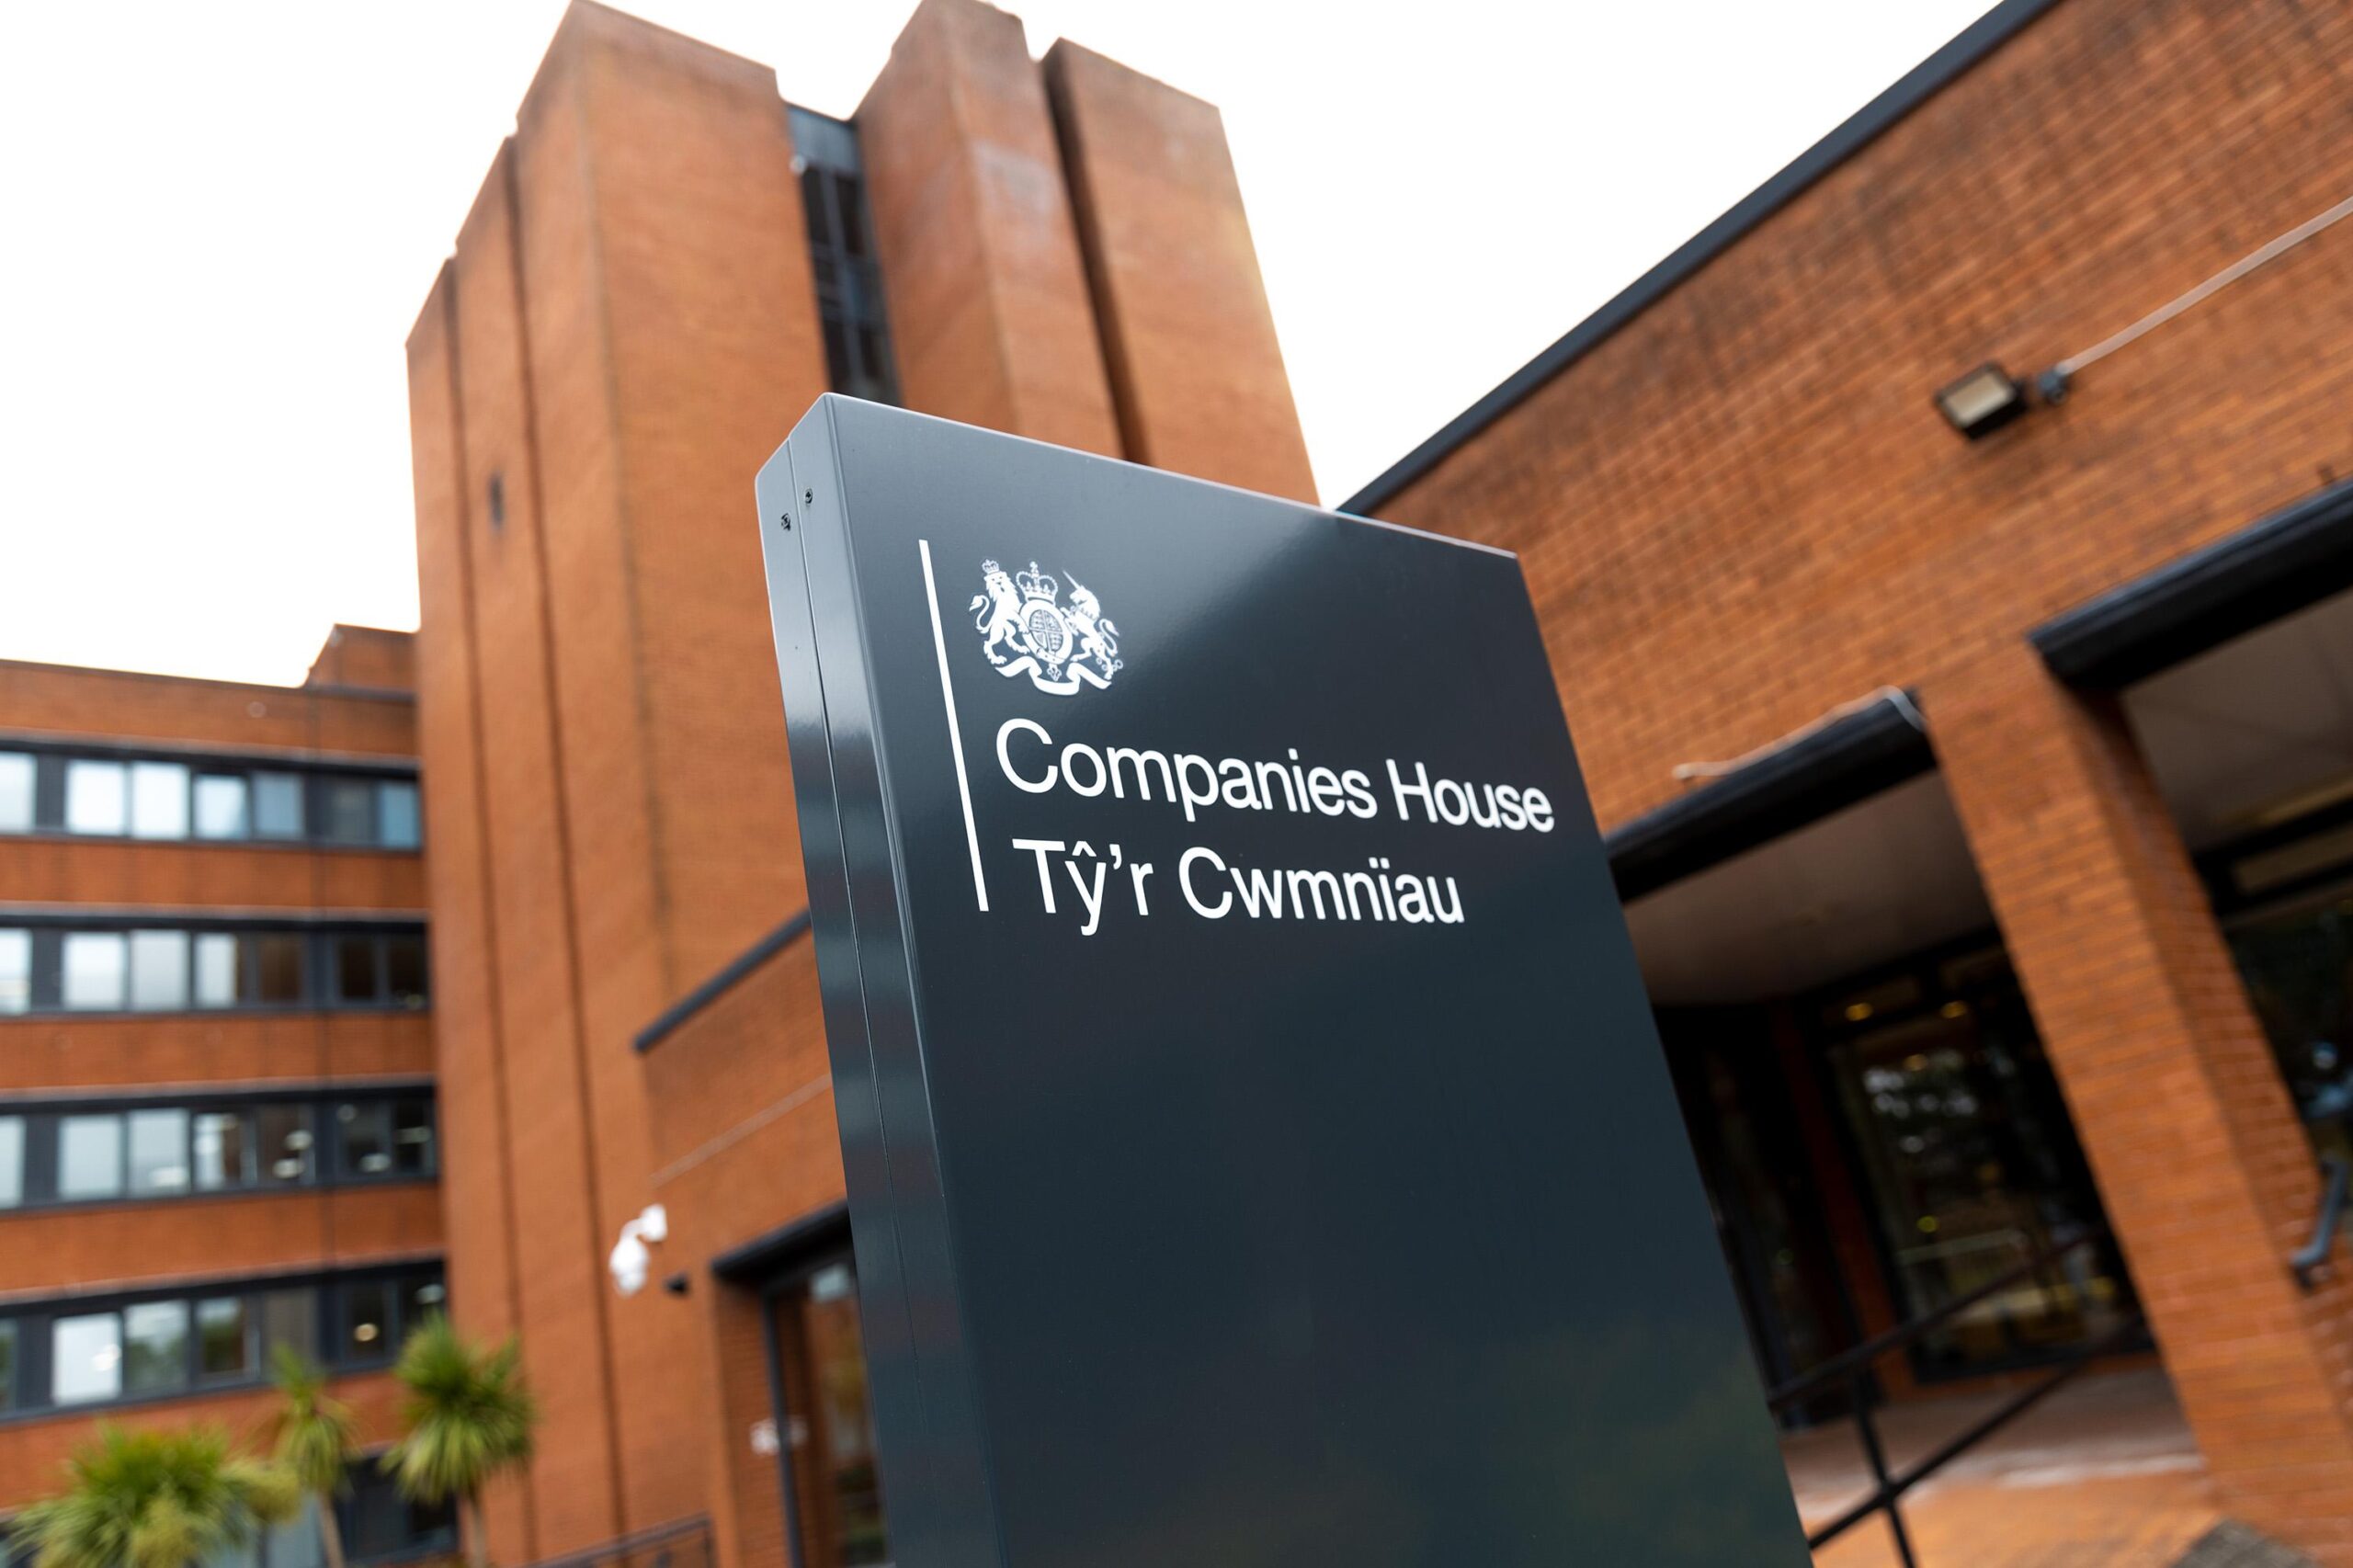
Small companies and micro-entities will need to file profit and loss accounts with Companies House from 1 April 2028. The government has confirmed the reform will go ahead, but smaller companies will be able to opt out of having their P&L accounts published on the public register.
For many business owners, this is a major change to company accounts filing. It means more information will need to be submitted to Companies House, even where some of that information may not be visible to the public If you are unsure about what is going to happen speak to your local accountant.
What is changing from April 2028?
From 1 April 2028, small companies and micro-entities will be required to file a profit and loss account as part of their annual accounts filing with Companies House.
A profit and loss account, often called a P&L, shows a company’s income, costs and resulting profit or loss for the year. At present, many small companies and micro-entities can file reduced information, meaning less financial detail appears on the Companies House register.
Under the new rules, smaller companies will still have to file the information, but they will be given the option to prevent their filed P&L account from being published publicly.
Will small company P&L accounts be public?
Not necessarily. Companies House has confirmed that small companies and micro-entities will be able to opt out of publication of their profit and loss accounts.
This means the P&L information will be filed with Companies House but, where the company chooses the opt-out, it should not appear on the public register.
However, the information will still be available to Companies House, HMRC and law enforcement agencies. The government’s aim is to improve financial transparency and help tackle fraud, economic crime and tax evasion, while addressing concerns about commercial confidentiality for smaller businesses.
Why does this matter for small businesses?
The change matters because many small business owners are used to filing limited accounts information. From April 2028, the accounts filing process will become more detailed and more structured.
For example, a small trading company that currently files minimal accounts may need to file a balance sheet and P&L account with Companies House. If it opts out of publication, competitors and customers should not be able to view the P&L on the public register, but HMRC and Companies House will still have access.
This makes it even more important to keep accurate accounting records throughout the year, rather than preparing figures only when accounts are due.
Abridged accounts will be abolished
The government has also confirmed that abridged accounts will be removed.
Abridged accounts are accounts prepared with reduced information, often used by smaller companies to limit what is shown in their public filing. Once the new rules take effect, this filing option will no longer be available.
This should simplify the filing framework, but it may also mean some companies need to change how their accounts are prepared and reviewed before submission.
No director’s report requirement for small companies
One planned measure will not now go ahead. The government has decided not to require small companies to file a director’s report as part of their annual report and accounts under these reforms.
This will be welcome news for many smaller businesses, as it avoids an additional reporting requirement that had caused concern during consultation.
Software-only filing will apply to all companies
From April 2028, all UK registered companies will need to file their accounts using commercial software.
Companies House has confirmed that web and paper-based accounts filing routes will close from this date. Accounts will need to be filed in Inline eXtensible Business Reporting Language, known as iXBRL.
In simple terms, iXBRL is a digital format that allows financial information to be tagged so it can be read and processed by software. Many accountants already use iXBRL for company tax returns and accounts filing, but businesses that currently file accounts themselves through Companies House web filing will need to prepare for the change.
Audit exemption statements will be strengthened
Companies claiming audit exemption will also need to provide a strengthened eligibility statement.
Audit exemption allows qualifying companies to avoid a statutory audit, provided they meet the relevant conditions. For financial years beginning on or after 6 April 2025, a private company may generally qualify by meeting at least two of the following conditions:
- annual turnover of no more than £15 million
- assets of no more than £7.5 million
- 50 or fewer employees on average
There are exceptions, so companies should not assume they qualify automatically. Some companies may be ineligible because of their structure, activities or group position.
What should company directors do now?
Although April 2028 may feel some way off, directors should start preparing early. Companies House has said businesses will have around 21 months to prepare, which is broadly one full accounting year plus nine months.
Practical steps include:
- checking whether your company qualifies as small or micro-entity under the current size thresholds
- reviewing how your accounts are currently prepared and filed
- moving to cloud or commercial accounting software if you still rely on manual records
- making sure bookkeeping is accurate and up to date throughout the year
- speaking to your accountant about how the P&L publication opt-out is expected to work
- reviewing audit exemption eligibility before accounts are filed
How Davenports can help
These Companies House filing reforms form part of the wider changes introduced through the Economic Crime and Corporate Transparency Act 2023. Some practical details, including the final opt-out process for P&L publication, are expected to be confirmed in secondary legislation and further guidance.
Davenports can help business owners understand how the changes may affect their company accounts, bookkeeping systems and filing obligations. We can also help ensure your accounts are prepared correctly and filed in the required format when the new rules take effect.
Key takeaway
From April 2028, small companies and micro-entities will need to file profit and loss accounts with Companies House, but they will be able to opt out of having those P&L accounts published publicly. Abridged accounts will be abolished, software-only filing will become mandatory, and audit exemption statements will face closer scrutiny.
The best approach is to prepare early. Good bookkeeping, suitable accounting software and timely advice will make the transition much smoother.
Need help preparing for the new Companies House accounts filing rules?
Get in touch with Davenports to review your current accounts process and plan ahead with confidence.
